

Salary increases: higher salaries may also reduce the tax burden
Salary increases continue to play an important role in the tax policy aimed at businesses.
For 2027, the proposal provides for a change in the reference percentage applicable to the incentive for salary increases, which falls from 4.6% to 4.5%.
This change is particularly relevant because it means that the decision to increase salaries should not be viewed solely as an increase in staff costs. Where the legally established requirements are met, higher employee remuneration may also be associated with tax advantages for the employer.
In practice, this creates an opportunity for companies to review their salary policies for 2027 in advance.
Instead of simply asking, “How much can we increase salaries?”, companies should consider a broader question:
How can we structure our remuneration policy in order to reward employees while making efficient use of the available tax incentives?
This analysis becomes even more relevant when combined with another important tool: employee bonuses.
Productivity bonuses: an increasingly relevant tool
Productivity and performance bonuses, profit-sharing schemes and balance sheet bonuses once again take on particular importance under the 2027 proposal.
The proposal provides for the continuation of the regime which, subject to compliance with the applicable conditions, allows an exemption from Portuguese Personal Income Tax (IRS) and Social Security contributions for bonuses of up to 6% of an employee’s annual base salary.
This measure may represent a particularly interesting opportunity for both companies and employees.
For companies, it allows reward mechanisms to be established based on results, performance or productivity. For employees, it may mean receiving additional remuneration under more favourable tax and social security conditions.
However, there is one essential point: simply describing a payment as a “bonus” is not sufficient for it to qualify for the regime.
The nature of the payment, the way in which it is awarded and compliance with the legally established conditions are crucial. These mechanisms should therefore be assessed before the amounts are awarded, rather than only when payroll is processed.
This is precisely why salary increases and bonuses should be considered together. A well-designed remuneration policy may combine increases in base salary with variable components linked to employee performance and company results.
Housing for employees: a new dimension of remuneration policy
One particularly interesting aspect of the 2027 State Budget is the use of taxation to encourage companies to play a role in addressing an issue that currently affects many employees: access to housing.
The proposal includes tax incentives relating to properties used to provide housing for employees, including the possibility for companies to double the tax depreciation allowance for properties used for this purpose.
This measure deserves particular attention.
For many years, employee remuneration packages have essentially been considered in terms of salary, company cars, health insurance and other fringe benefits. Pressure on the housing market is now making employer-provided accommodation an increasingly relevant component of employee benefit packages.
Housing may therefore become an important tool for attracting and retaining talent, particularly in areas where accommodation costs represent a significant proportion of employees’ income.
Public policy for 2027 also recognises the importance of housing, with significant investment planned for the promotion and rehabilitation of housing and to increase housing supply.
Salaries, bonuses and housing: looking at remuneration as a whole
The real potential of these measures becomes apparent when they are no longer considered in isolation.
Consider, for example, a company planning to review employee remuneration in 2027. Rather than allocating its entire available budget exclusively to a uniform salary increase, it may be worth considering a combination of:
- increases in base salaries;
- productivity or performance bonuses;
- profit-sharing arrangements;
- balance sheet bonuses;
- housing-related benefits;
- other non-salary benefits suited to employees’ circumstances.
Naturally, there is no one-size-fits-all solution.
The most efficient model will depend on the company’s salary structure, the number and profile of its employees, its human resources policy, its financial results and, above all, compliance with the legal and tax requirements associated with each benefit.
This is precisely why planning should take place before salary increases and bonuses are processed.
The 2027 State Budget may be an opportunity to review salary policies
The increase in Portugal’s National Minimum Wage to €970 in 2027 is also a factor that companies will need to incorporate into their salary planning.
However, a review of remuneration should not be limited to updating the lowest salaries.
An increase in the minimum wage can have consequences across different salary levels and may require a broader review of the company’s salary structure, particularly where the business also intends to meet the requirements for incentives associated with salary increases and the payment of bonuses.
The end of 2026 may therefore be the right time to model different scenarios before making decisions for 2027.
An apparently small difference in the percentage of a salary increase, the timing of a bonus or the way in which a particular benefit is structured can translate into a significant difference in the tax and social security burden for both the company and the employee.
Conclusion
The 2027 State Budget Proposal reinforces an increasingly clear trend: employee remuneration should not be considered solely in terms of monthly salary.
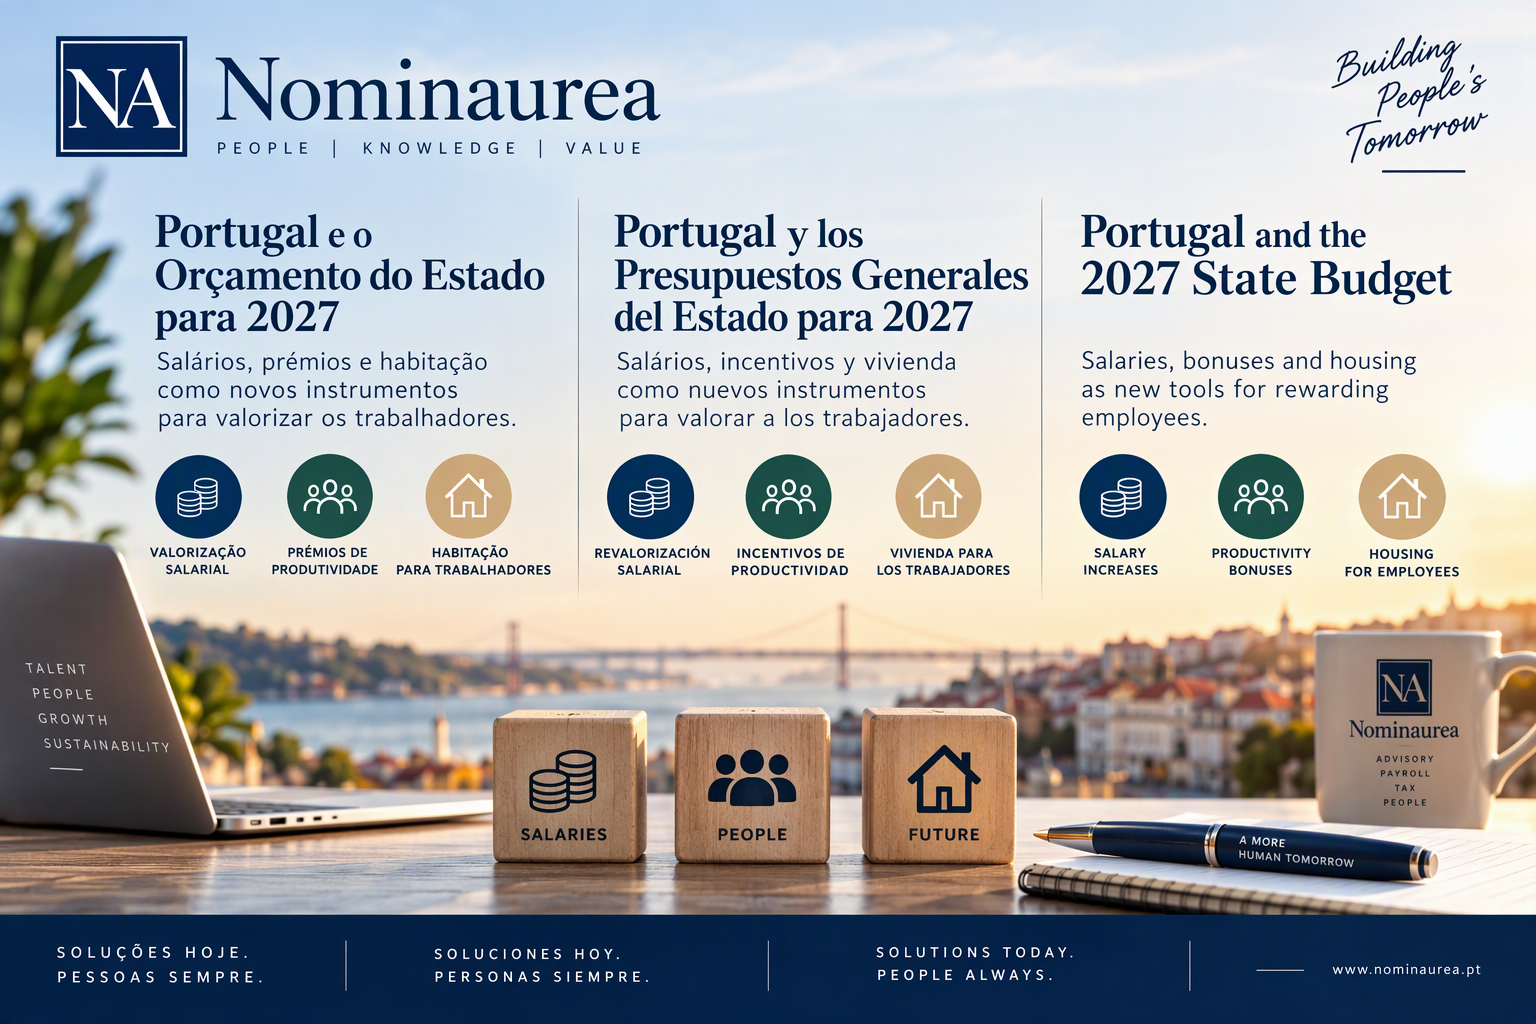
Salary increases, productivity bonuses and housing-related benefits may form part of an integrated strategy capable of bringing together three objectives that have traditionally been difficult to reconcile: rewarding employees, controlling business costs and improving the tax efficiency of remuneration.
However, these benefits are not automatic. There are conditions, limits and requirements that must be assessed in each individual case. Furthermore, as the 2027 State Budget is still at the proposal stage, the measures may be amended before final approval.
The message for businesses is therefore straightforward: 2027 should not start in January. Salary and tax planning should begin in 2026.
How can Nominaurea help?
At Nominaurea, we can help businesses prepare their remuneration policies for 2027 by combining tax, accounting, employment and payroll expertise.
Advance planning makes it possible to assess different salary increase scenarios, consider the potential use of bonuses and other employee benefits, and determine their respective tax and social security implications before decisions are made.
Our aim is to turn the changes proposed for 2027 into an opportunity to develop a remuneration policy that is more efficient, competitive and tailored to the specific circumstances of each business.
Before increasing salaries or awarding bonuses in 2027, it pays to do the numbers.