

Self-Employed Workers in Portugal: November Is the Time to Review Your Contribution Regime
The income of a self-employed professional is not always consistent throughout the year. Some businesses experience seasonality, periods of higher turnover, temporary reductions in activity or significant changes in their client portfolio.
As a result, the way in which the basis for Social Security contributions is determined can have a significant impact on a professional’s cash flow and financial planning.
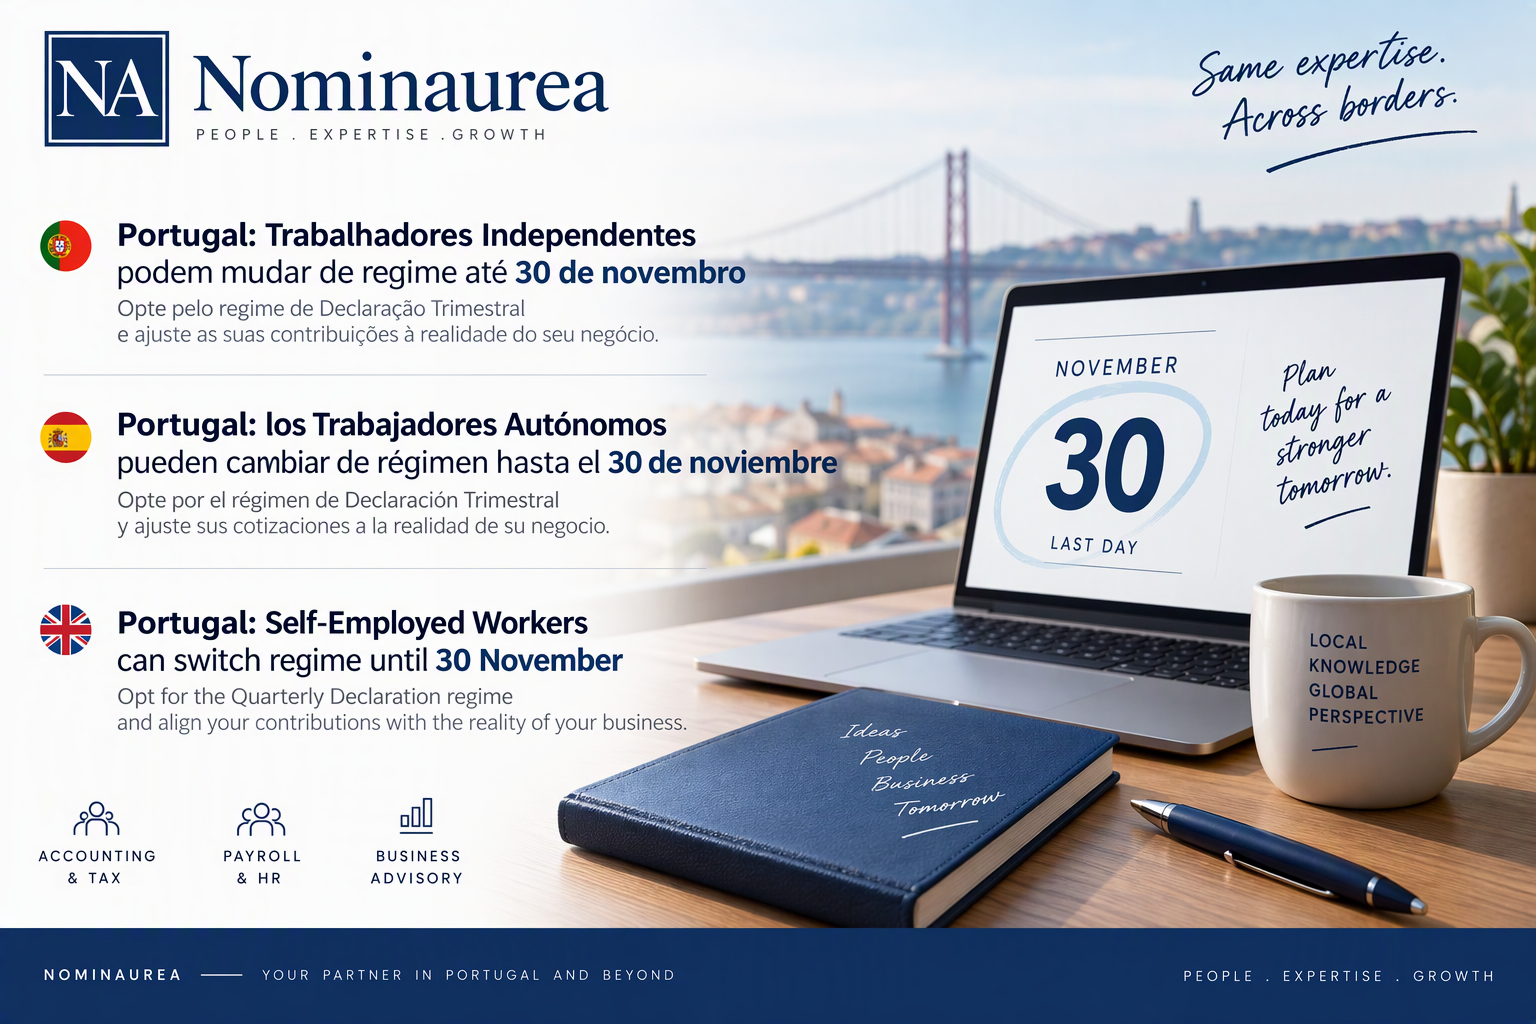
Self-employed workers covered by the organised accounting regime may, during November, choose to switch to the Quarterly Declaration regime. The option can be exercised until 30 November and takes effect in the following calendar year.
This should therefore not be regarded simply as an administrative procedure. It is a decision that should be considered carefully, taking into account each professional’s individual circumstances and expected business performance.
What Is the Main Difference Between the Two Regimes?
Under the organised accounting regime, the contribution basis is linked to the taxable profit assessed for the previous period, in accordance with the applicable rules.
By opting for the Quarterly Declaration regime, the self-employed worker moves to a system that more closely follows the recent income generated by their activity, through the periodic declarations required under this regime.
Portuguese Social Security rules establish the quarterly declaration requirement for self-employed workers covered by this regime, together with specific rules for determining relevant income and the corresponding contribution basis.
In practice, switching regimes may be particularly relevant when there is a significant difference between previously assessed taxable profit and the level of activity expected for the following year.
Why Might the Quarterly Declaration Regime Be Worth Considering?
One of its main characteristics is that it enables Social Security contributions to be more closely aligned with the recent financial performance of the professional activity.
For some self-employed workers, this may provide:
- greater alignment between contributions and business performance;
- a better adjustment where income fluctuates throughout the year;
- greater predictability when managing cash flow;
- easier integration of Social Security contributions into ongoing financial planning;
- less dependence on taxable profit from an earlier period when determining the contribution basis.
However, this does not mean that the Quarterly Declaration regime will automatically be more advantageous for every self-employed worker.
The decision should be made after comparing both regimes and, whenever possible, estimating the expected contribution impact for the following year.
How Can You Switch Regimes?
The procedure can be completed entirely online.
Until 30 November, self-employed workers can log in to the Portuguese Social Security Portal and follow this route:
Trabalho > Remunerações e contribuições > Trabalhadores independentes > Alterar opção de regime de contabilidade organizada para declaração trimestral
The menu descriptions have been kept in Portuguese so that users can identify the relevant options directly on the Portuguese Social Security Portal.
Through this service, workers can consult information relating to the taxable profit of the previous year and the contribution regime applicable in the following year.
Until the last day of November, it is also possible to amend the most recent choice made, including cancelling the option to move to the Quarterly Declaration regime, in accordance with the procedures available on the Portal.
Before Switching, Do the Calculations
Although a contribution system that more closely reflects recent income may appear attractive, the decision to change regimes should always be assessed on an individual basis.
Before making a decision, particular attention should be paid to the following factors:
1. Current Income From the Activity
Compare recent turnover and income with the figures currently used to determine your contribution position.
2. Expectations for the Following Year
If you expect your business to grow, activity to decline or significant seasonal fluctuations, these projections should be taken into consideration.
3. The Impact on Cash Flow
Rather than looking only at the amount of an individual contribution, it is advisable to consider the cumulative financial impact over the entire year.
4. Reporting Obligations
Moving to the Quarterly Declaration regime also means complying with the periodic reporting obligations associated with this system.
It is therefore important to consider not only the potential financial impact but also the administrative obligations resulting from the change.
5. Your Individual Circumstances
Other professional activities, possible exemptions and specific individual circumstances can significantly affect the outcome of the analysis.
For this reason, the decision should be based on a direct comparison of the two regimes rather than on the assumption that one regime is automatically better than the other.
Remember the 30 November Deadline
This decision is subject to a specific deadline.
Self-employed workers covered by the organised accounting regime who wish to opt for the Quarterly Declaration regime must make their choice by 30 November, with the new regime taking effect in the following calendar year.
Leaving the decision until the final days of November can make it more difficult to carry out a proper assessment of the alternatives.
It is therefore advisable to plan ahead, review the activity’s financial figures and estimate the contribution impact under each scenario.
Conclusion
For self-employed workers in Portugal covered by the organised accounting regime, November provides an opportunity to review how their Social Security contributions will be determined in the following year.
Opting for the Quarterly Declaration regime can enable contributions to reflect more recent income levels. However, the change should not automatically be regarded as financially advantageous.
Each situation should be assessed according to current income, expected business performance, the obligations associated with each regime and the respective financial impact.
The key point is not to miss the deadline: 30 November.
How Can Nominaurea Help?
At Nominaurea, we can help self-employed workers assess which contribution regime is best suited to their professional and financial circumstances in Portugal.
Our team can assist you with:
- reviewing your current Social Security position as a self-employed worker in Portugal;
- comparing the organised accounting and Quarterly Declaration regimes;
- assessing the potential impact of changing regimes on contributions and cash flow;
- supporting compliance with the accounting, tax and Social Security obligations associated with your activity;
- planning for the next financial year;
- clarifying questions concerning the tax and Social Security framework applicable to self-employed workers in Portugal.
Before changing regimes, make sure you have done the calculations. A decision made now could affect the financial management of your activity throughout the entire following year.